The Bolsa Família program supports eligible households across Brazil. This guide explains current loan rules, existing contracts, safety, and alternatives.
It also covers checks before considering credit. Understanding the current policy helps families avoid outdated information.
What Is the Bolsa Família Loan?
The former Auxílio Brasil payroll loan allowed certain beneficiaries to repay credit through deductions from their monthly benefit. Under current Bolsa Família rules, new payroll-loan contracts deducted from Bolsa Família are no longer permitted.
Who Can Apply for the Bolsa Família Loan?
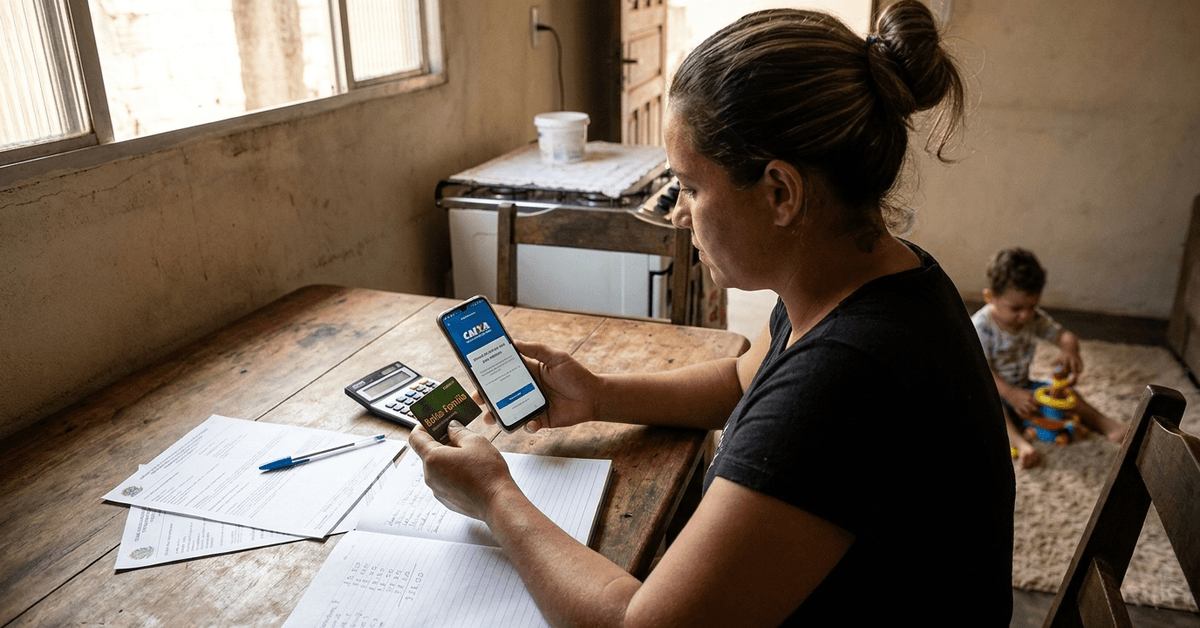
Since June 2023, beneficiaries cannot enter new consignado contracts deducted from Bolsa Família. Anyone researching a Bolsa Familia loan application should distinguish current rules from older Auxílio Brasil information.
- Older contracts may continue until settled.
- Receiving Bolsa Família does not create automatic eligibility for a separate bank loan.
- Banks may offer separate credit under their own criteria.
- Benefit status should never guarantee loan approval.
Key Requirements for the Bolsa Família Loan Process
There are no current application requirements because new Bolsa Família payroll contracts are prohibited. Other credit products follow each lender’s eligibility rules.

- An active CPF and valid identification may be requested.
- Current address and contact information may be required.
- Income or repayment capacity may be reviewed for ordinary credit.
- Cadastro Único information should remain updated.
- Beneficiaries should verify lenders before sharing personal data.
How Does the Application Work? A Step-by-Step Walkthrough
There is no official process for new Bolsa Família payroll credit. These verification steps can help assess credit claims and alternatives.
1. Confirm Program Participation
Check household information and benefit status through official channels. This status check separates Bolsa Família administration from unrelated financial offers. Benefit participation does not authorize new loan deductions.
2. Update the Cadastro Único
Accurate Cadastro Único information remains important for Bolsa Família administration. Address, household, or income changes should be reported through appropriate social services. Updating the registry does not create eligibility for a prohibited consignado loan.
3. Consult Financial Institutions Carefully
Banks may offer credit products separate from Bolsa Família. Anyone searching how to apply for empréstimo Bolsa Família should confirm the offer is not falsely presented as government-backed payroll credit. Legitimate lenders should explain rates, fees, repayment, and approval criteria clearly.
4. Assemble Required Documents
For ordinary bank credit, documentation depends on the product and lender. Common requests may include identity and address records, income information, or account details. Beneficiaries should provide documents only through verified channels.
5. Visit Your Bank or Use an Official App
Beneficiaries comparing independent credit can use a bank branch, verified website, or official app. Official CAIXA information confirms that new Consignado Auxílio Brasil contracts remain suspended.
This official confirmation is more reliable than advertisements claiming immediate Bolsa Família payroll credit.
6. Analyze Any Loan Proposal
A legitimate proposal should show the amount borrowed, interest, fees, installments, and total repayment.
Comparing the effective cost with household income can reveal whether payments are manageable. No lender should describe Bolsa Família as guaranteed collateral for a new consignado contract.
7. Finalize Only a Valid Contract
If a beneficiary chooses separate legal credit, the agreement should match published lender terms. Read the complete contract before accepting, especially repayment dates and penalties.
Independent credit should follow its own rules rather than being presented as a new Bolsa Família deduction.
Interest Rates and Loan Limits: What to Expect
There is no current interest cap or borrowing limit for new Bolsa Família consignado contracts because they are not allowed. Existing older contracts remain governed by the terms that applied when signed.
Beneficiaries considering separate personal credit should compare disclosed costs. People researching how to get Bolsa Familia credit should understand that benefit receipt does not create a special loan entitlement.
Risks, Considerations, and Cautions
Outdated advertisements may still describe the former Auxílio Brasil lending model as available. Beneficiaries should treat loan promises carefully and verify claims through official channels.
- Benefit deductions: Existing older contracts may still have installments deducted.
- Separate debts: Ordinary personal loans create obligations independent of Bolsa Família.
- Household budget: Debt can reduce money available for essential expenses.
- Fraud risks: Requests for advance payments, passwords, or PINs are warning signs.
- Misleading advertising: Guaranteed government loan claims should be verified.
Where to Find Help and Answers to Common Questions
Official sources are the best place to verify Bolsa Família rules and older contracts. Using trusted information can prevent confusion caused by outdated websites or advertisements.
- The Ministry of Development and Social Assistance provides current Bolsa Família guidance.
- CAIXA publishes information about older Consignado Auxílio Brasil contracts.
- Local CRAS units can assist with Cadastro Único and benefit questions.
- Consumers can contact the lender responsible for an existing contract.
Tips for a Healthier Relationship with Government Loans
Bolsa Família should not be treated as an automatic pathway to borrowing. Families comparing Brazil social loans or private credit should focus on affordability and legitimacy before accepting obligations.
- Review the household budget before borrowing.
- Compare interest, fees, total repayment, and duration.
- Keep benefit administration separate from private credit decisions.
- Never share passwords, PINs, or verification codes with promoters.
- Use official portals and regulated institutions to verify offers.
Frequently Asked Questions About Bolsa Família Loan Applications
Rules differ from those that applied to Auxílio Brasil consignado lending. These common questions clarify what beneficiaries can expect today.
Who sets the loan terms and updates for Bolsa Família loans?
Federal law and program regulations determine whether benefit-linked deductions are permitted. Current Bolsa Família legislation does not allow new consignado borrowing deducted from the benefit. Banks administer older contracts under applicable agreements and rules.
Can a denied or suspended benefit still access a loan?
A suspended Bolsa Família payment does not provide access to a new benefit-linked payroll loan. Separate bank credit may have unrelated eligibility standards. Borrowers should not assume benefit status guarantees approval elsewhere.
Is early repayment possible, and does it lower future deductions?
For an older consignado contract, early repayment may be possible under applicable rules. Paying the outstanding balance can end future deductions when the debt is fully settled. The borrower should request an updated payoff amount from the lender.
Are there consequences for failing to repay the loan?
Existing debts remain payable even if the social benefit changes or stops. Missed payments on separate credit can lead to collections, charges, or negative credit reporting. Borrowers facing difficulties should contact the lender promptly.
Conclusion
New payroll loans deducted from Bolsa Família are not currently permitted. Understanding the current rules helps families avoid confusing old Auxílio Brasil information with today’s program.
Beneficiaries can still evaluate independent credit, but approval, costs, and repayment depend on the lender. Using official sources and reviewing total affordability can support safer financial decisions.